
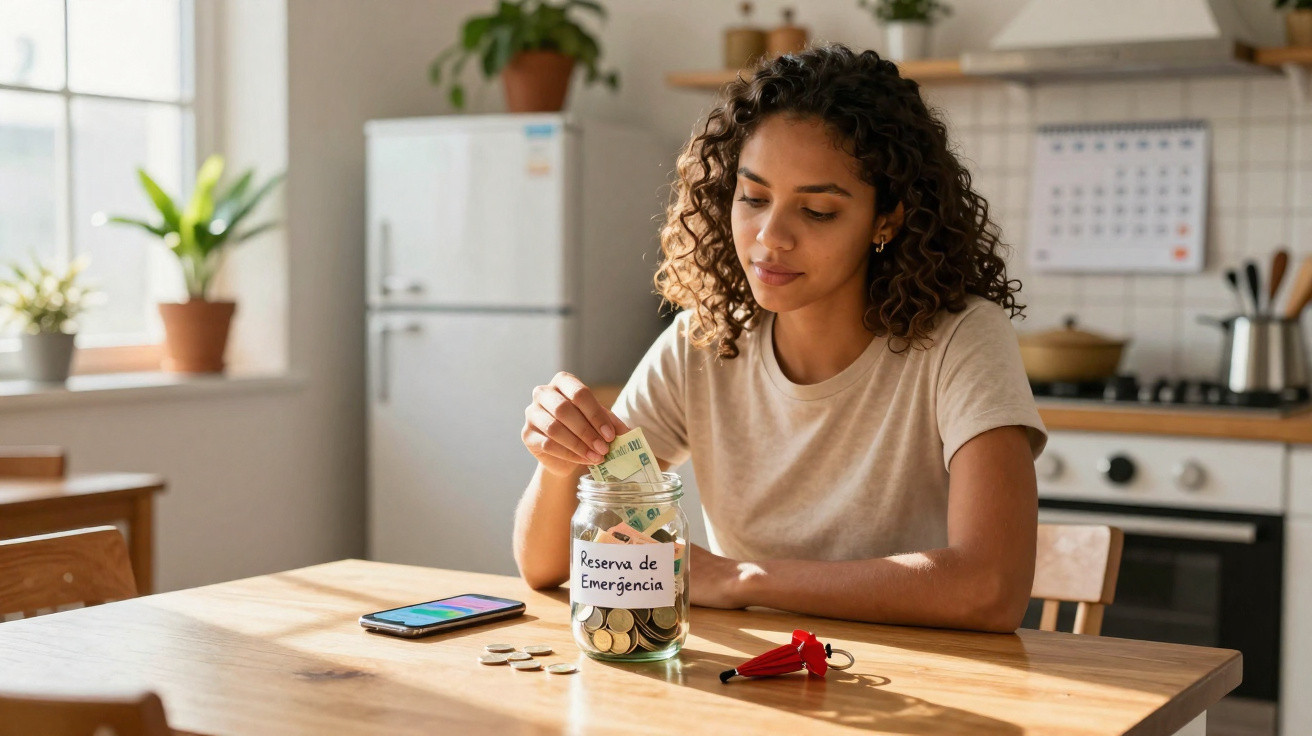
An emergency fund is money set aside solely for unexpected circumstances, such as health problems, unemployment, urgent repairs, or any event requiring immediate cash. Unlike long-term investments or savings earmarked for particular goals, it serves one clear purpose: to prevent unforeseen events from becoming debt.
Without this safeguard, unplanned costs are often covered with credit cards, overdrafts or loans - options that carry high interest rates and can strain a budget for months or even years.
How much to save in an emergency fund
The right size of an emergency fund depends on your financial circumstances, income security and lifestyle. The guideline most commonly used by experts is to build up an amount equal to several months of essential outgoings, rather than your total salary.
This calculation should include vital costs such as housing, food, household bills, transport and healthcare. The aim is to provide enough time to get your finances back on track without panic if your income stops.
Emergency fund: how much to save and where to keep the money
- Between 3 and 6 months of expenses for people with a stable income
- Between 6 and 12 months for self-employed people or professionals with variable income
- Highly liquid accounts or investments that allow quick withdrawals
- Low-risk options, even where returns are lower
The priority for an emergency fund is not return, but immediate access to the money when it is needed.
Where to keep an emergency fund
As this money may be required at any time, an emergency fund should be held in safe, liquid products. Common choices include interest-paying accounts, conservative fixed-income funds and variable-rate securities with daily access.
Higher-risk investments, including shares, cryptocurrencies and property funds, are not suitable for this purpose. Market fluctuations may reduce their value at precisely the point when the money is most needed.
Why not leave this money in a current account?
Keeping an emergency fund in a current account may make it easier to access, but it also increases the risk of using it for the wrong reasons. Having it alongside day-to-day money can encourage impulse spending and weaken financial discipline.
Placing the fund in a separate account or investment helps establish a psychological boundary, making it clear that the amount is not part of the monthly budget and should only be used in genuine emergencies.
How to build an emergency fund even on a low income
Creating an emergency fund does not require large initial contributions. Consistency matters most. Small sums saved each month build the habit and, over time, create meaningful protection.
Automating transfers immediately after receiving your income is an effective approach. This means the money is saved before it can be spent, avoiding the feeling that “there is nothing left” at the end of the month.
When to use - and not use - an emergency fund
An emergency fund should only be used for unexpected and unavoidable situations. Holidays, planned purchases and consumer wants do not meet this definition. Using it inappropriately weakens your financial protection and can lead to further difficulties.
Once money has been withdrawn, the best approach is to replenish it as soon as possible, so that the safety net remains available.
Financial security starts with prevention
An emergency fund is the first step towards a more balanced financial life. It eases anxiety, prevents rushed decisions and gives you time to act clearly during difficult periods.
Before considering more complex investments, securing this foundation is essential. After all, no financial plan can stand without a safety net for life’s unexpected events.
Comments
No comments yet. Be the first to comment!
Leave a Comment