
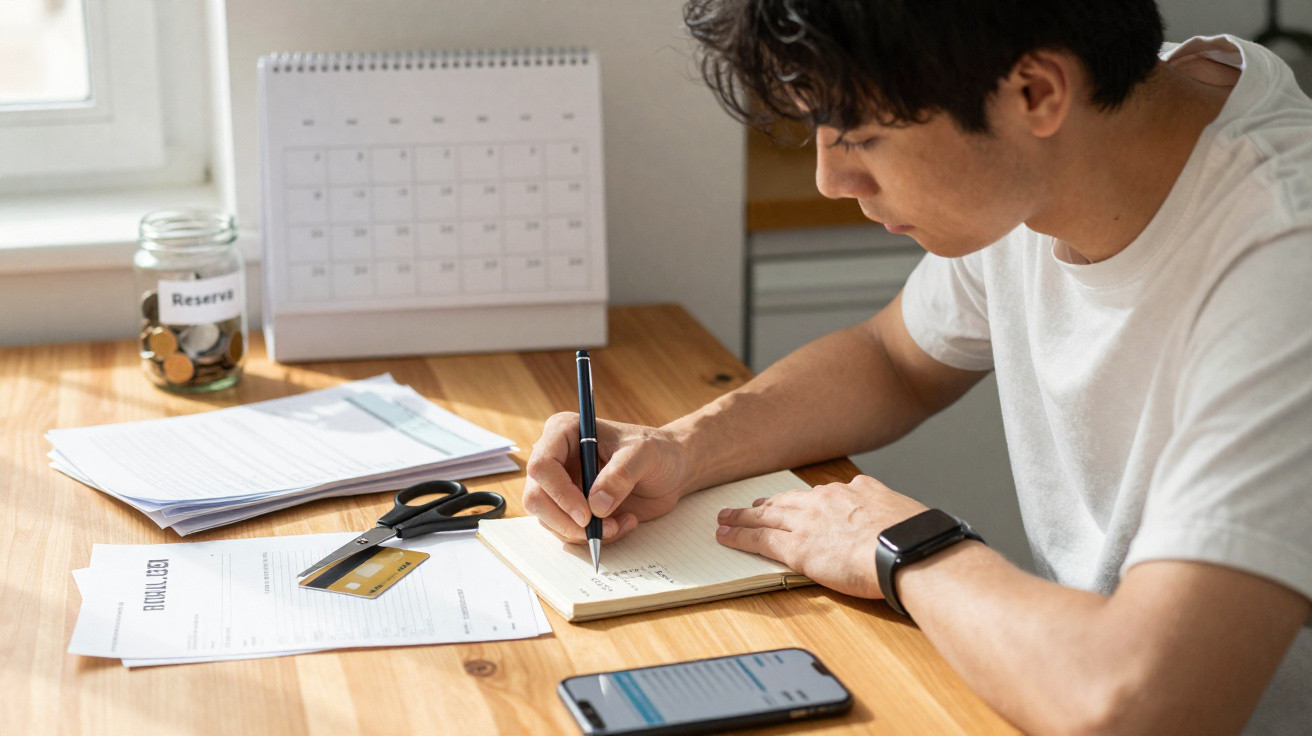
An unexpected bill, relying on an overdraft to make it to the end of the month, or finding that your salary runs out before payday can all cause anxiety and leave you feeling out of control. Once debts begin to build up, it is easy to assume that sorting out your finances requires a major life change. In reality, it starts with small, practical actions.
The first 30 days are crucial for breaking the debt cycle. This is the time to spot the issues, see where your money is going and put a strategy in place that lets you regain some financial breathing room.
Start by facing the figures
Many people avoid checking bank statements, credit card bills and payment notices because they are afraid of discovering the scale of the problem. Yet overlooking debts usually allows them to become even larger.
Set aside time to make a list of every outgoing payment, debt and source of income. Include credit cards, loans, finance agreements, overdue bills and any other financial obligation.
The purpose is not to be alarmed by the amounts, but to understand precisely where you currently stand. Without this assessment, creating an effective plan is impossible.
Identify spending you can cut straight away
During the first few days, review every expense carefully. Small costs can seem insignificant individually, but together they may account for a substantial part of your budget.
Subscriptions you barely use, paid apps, impulse purchases, frequent takeaway orders and regular leisure spending can all be temporarily reconsidered.
This does not mean removing everything that brings you enjoyment. It means separating what is essential from what can wait until your finances are more stable.
Stop taking on new debt
One of the most important steps is to prevent the snowball from getting bigger.
Where possible, avoid unnecessary instalment plans, credit purchases and using emergency borrowing facilities such as an overdraft or a credit card’s revolving credit. These options often charge high interest and can make financial recovery even harder.
For the first 30 days, the priority should be to stabilise your position rather than add to future commitments.
Build a simple, realistic budget
You do not need complicated spreadsheets to get your finances organised. A sheet of paper, an app or a basic spreadsheet will do the job.
Write down your monthly income, then allocate the amounts across essential costs, debt repayments and variable spending.
What matters most is setting a budget you can genuinely stick to. Unrealistic targets often lead to frustration and abandoning the plan altogether.
Negotiate your debts as soon as possible
Many people postpone negotiations because they think they must have enough money to clear the full balance. In fact, many creditors offer instalment arrangements, discounts and special repayment terms to help settle outstanding debts.
Speaking to banks, finance providers and companies may uncover more affordable options than you expect.
Give particular priority to debts carrying the highest interest, as these are likely to increase more quickly.
Look for ways to increase your income
Although reducing spending matters, bringing in additional money can speed up your recovery considerably.
In the first 30 days, consider temporary work, providing services, selling items you no longer use or taking on extra activities that fit around your usual routine.
Even modest additional earnings can be put towards debt repayments and help reduce the interest that builds up.
Make tracking daily spending a habit
A lack of budget monitoring is one reason many people fall back into debt.
Recording your spending every day helps you spot consumption patterns and correct overspending before it develops into a bigger issue.
This check takes only a few minutes each day, yet it can make a meaningful difference over time.
Aim for progress, not perfection
Getting out of debt is rarely a straightforward process. Unexpected events occur, unplanned costs arise and some months will be tougher than others.
For that reason, the aim of the first 30 days is not to solve every financial problem immediately, but to establish a solid foundation for recovery.
Each renegotiated debt, every expense avoided and every pound saved is progress. With organisation, discipline and a realistic plan, a difficult period can become a turning point towards healthier, more balanced finances.
Comments
No comments yet. Be the first to comment!
Leave a Comment