
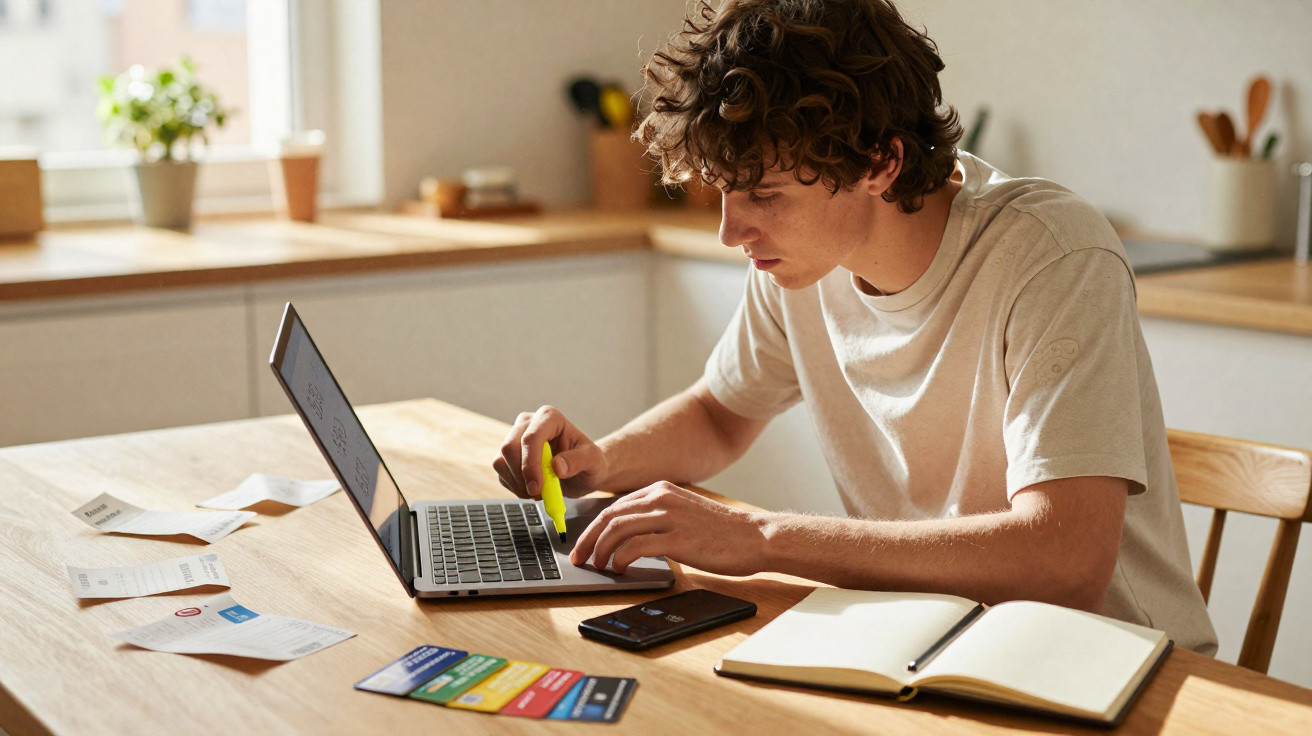
A debt does not always begin with a major purchase or an unforeseen emergency. In many instances, it develops quietly, fuelled by minor expenses that seem harmless when considered one at a time.
This is known as a financial leak. These are costs that slip out of control without providing a matching benefit and, gradually, reduce your ability to save, invest or deal with unexpected events.
The issue is that such leaks often go unnoticed. By the time they are recognised, your budget may already be under strain.
The good news is that there are signs that can expose these losses before they become a bigger problem.
What is a financial leak?
A financial leak is any recurring or unnecessary expense that uses up money without you realising its true effect.
Unlike essential outgoings, such as housing, food and transport, these expenses generally arise from habit, distraction or a lack of monitoring.
Individually, they may appear insignificant. Added together over several months, however, they can amount to substantial sums. The risk lies precisely in how difficult they can be to spot.
The first sign: money disappears without an explanation
Have you ever been paid and, just a few days later, felt as though the money had simply vanished?
This is one of the most common signs of financial leaks.
When you have no clear idea of where your money is going, small expenses are likely building up without control.
If, at the end of the month, you cannot account for exactly how you used a significant part of your income, it is worth examining your spending habits more closely.
Forgotten subscriptions can cost more than they seem
Streaming services, apps, digital platforms, subscription clubs and online tools often charge relatively small amounts. As a result, they can easily go unnoticed.
The problem begins when several subscriptions build up over time.
A monthly charge of £20 may seem unimportant. Five or six similar charges can add up to hundreds or even thousands of pounds over a year.
Reviewing direct debits regularly is a straightforward way to remove unnecessary spending.
Recurring impulse purchases need attention
Not every impulse purchase causes financial harm. The danger arises when this behaviour becomes routine.
Frequent app-based orders, irresistible offers, stress-driven purchases or products bought simply because they were discounted can create a constant stream of money going out.
A useful exercise is to check your bank statement for the past 30 days and see how many purchases were not planned.
The result is often surprising.
Small expenses count too
Many people track only high-value outgoings and overlook smaller ones.
Yet repeated small purchases are often the very expenses most likely to escape notice.
Coffees, snacks, delivery fees, ride-hailing journeys, convenience-store purchases and unplanned items can account for a significant share of your budget.
The question should not be “how much does it cost today?”, but “what does it add up to over a month or a year?”.
Your credit card can reveal hidden financial leaks
Your card transaction history is a valuable tool for identifying spending patterns.
When reviewing your statement, look for:
Repeated purchases
Similar expenses made several times during the month.
Automatic charges
Services that are still being paid for despite not being used regularly.
Emotional spending
Purchases made during periods of stress, anxiety or boredom.
Unknown subscriptions
Charges that have gone unnoticed for several months.
This review can uncover habits that were invisible in day-to-day life.
How to carry out a personal financial audit
An effective way to find financial leaks is to carry out a simple audit.
For one month, record every expense, regardless of its value.
At the end of that period, sort your spending into three groups:
Essential – Housing, basic food, transport and healthcare.
Important – Leisure, education and activities that improve quality of life.
Non-essential – Expenses you would not miss, or which could be reduced.
This assessment often makes the best saving opportunities clear.
Preventing financial leaks is easier than getting out of debt
Once a debt arises, you will usually need to reorganise your budget, reduce spending and deal with interest.
For that reason, identifying financial leaks before they grow is a far more effective approach.
Small changes made today can prevent major worries in the future.
After all, financial health depends not only on how much money comes in, but also on your ability to see where it is going out.
Comments
No comments yet. Be the first to comment!
Leave a Comment